Punters' Playground Shifts: Fresh Trends Sweeping Britain's Betting Scene
Petra Klein · Apr 2, 2026
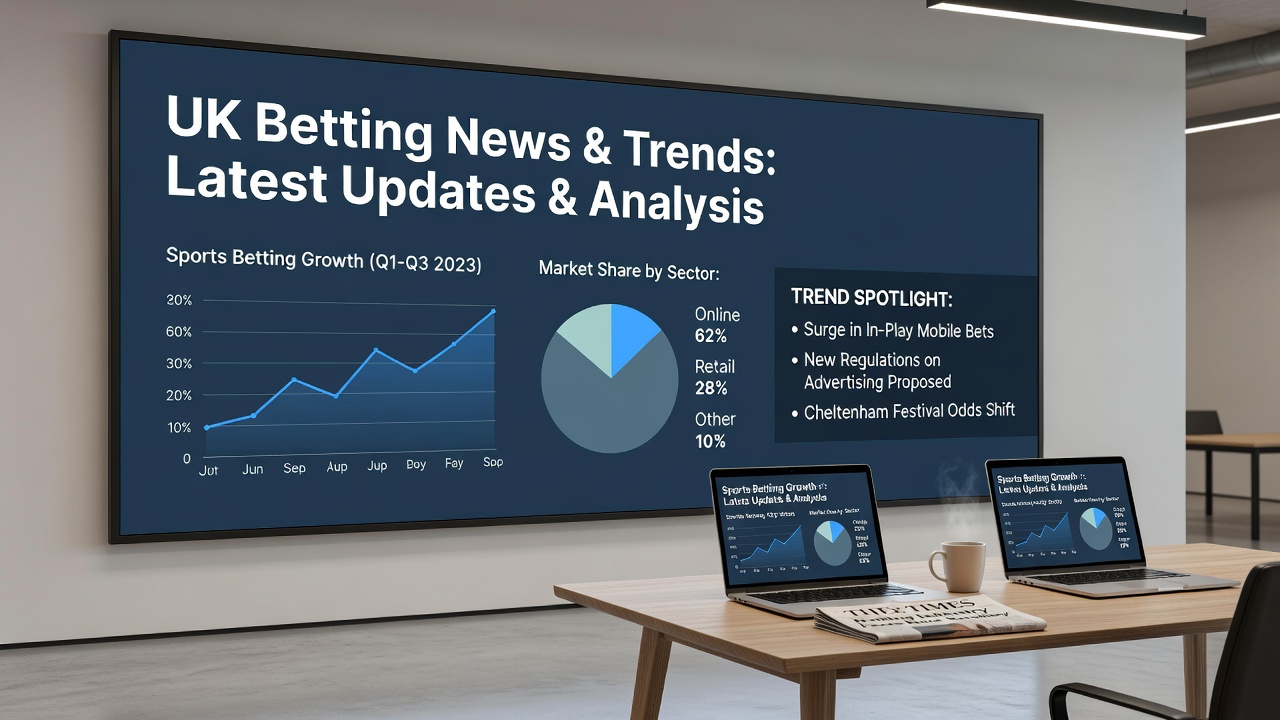
UK Gambling Yield Climbs to £4.3 Billion in Late 2025 Quarter as Remote Sectors Power Ahead
Observers tracking the UK gambling landscape have zeroed in on fresh figures from the UK Gambling Commission, which dropped its latest quarterly report covering July through September 2025; that data paints a picture of steady expansion, with the gross gambling yield hitting £4.3 billion across Great Britain, a solid 6.6% jump from the same stretch in 2024.
Remote Casinos and Lotteries Steer the Surge
What's driving this uptick becomes clear when experts drill into the breakdowns, as remote casinos and lotteries emerge as the heavy hitters fueling the growth; data indicates remote casino GGY soared while lotteries posted strong gains too, together pushing the overall sector forward amid a landscape where digital platforms continue to dominate daily plays.
Take the remote casino segment, for instance: figures reveal it led the charge with notable increases, reflecting how operators have leaned into online innovations that keep players engaged longer; lotteries, on the other hand, benefited from seasonal draws and consistent ticket sales, which observers note often spike during summer months when leisure spending loosens up.
And while the total GGY reflects this momentum, it's worth highlighting how these remote sectors now anchor the industry's financial pulse, especially as land-based venues hold their ground without the same fireworks.
Land-Based Slots Show Resilience
Land-based fruit and slot machines, a staple in pubs and arcades, generated £680 million in GGY over the quarter, maintaining stability even as the broader industry expanded; researchers point out this figure underscores a segment that's weathered shifts toward online alternatives, with steady foot traffic and machine upgrades keeping revenues level.
People familiar with the beat know these machines often serve as the entry point for casual gamblers, and their consistent output signals that physical venues aren't fading quietly; instead, they complement the remote boom, creating a balanced ecosystem where both worlds coexist.
Now, fast-forward to April 2026, when these stats landed in the public eye, and analysts wasted no time parsing what they mean for the year ahead; the Gambling Commission's industry statistics report for financial year April 2025 to March 2026, Q2 edition, arrived right on cue, offering a snapshot that's already shaping operator strategies and regulatory chats.
Adult Participation Holds Firm at 48%
Gambling Survey for Great Britain data from Wave 3, spanning July to October 2025, shows adult participation sticking at 48%, a figure that researchers describe as remarkably steady despite the revenue climb; this stability suggests the growth stems from higher spending among existing players rather than a flood of new ones jumping in.
Experts who've pored over past waves note how participation has hovered in this range for quarters now, which is significant because it points to a mature market where operators focus on retention tools like personalized offers and seamless apps; that's where the rubber meets the road for sustainability, as steady numbers paired with rising yields often signal deeper engagement.
But here's the thing: while participation remains unchanged, the data hints at subtle shifts in how people gamble, with remote options drawing more time from those 48% who partake; one study highlighted in related surveys found that online sessions averaged longer durations, contributing to the GGY lift without pulling in fresh faces.
Sector Breakdowns Reveal Nuanced Growth
Diving deeper, the report lays out GGY across key verticals, where betting sectors showed modest gains alongside teh remote casino and lottery fireworks; for example, non-remote betting edged up slightly, buoyed by sports events that kept punters active through the summer.
Online betting, meanwhile, contributed handsomely to the total, as platforms rolled out features that synced with live events; observers tracking these trends have seen how integration of real-time data and mobile access amplifies yields, turning casual wagers into sustained activity.
Land-based casinos, though, presented a mixed bag with some stability but no big leaps, which aligns with the fruit machine story; data shows their GGY held firm, proving that high-street appeal endures even as digital rivals shine brighter.
Comparing to Prior Periods
When stacked against Q3 2024, the 6.6% rise stands out, yet experts caution that seasonal factors like major sporting calendars played a role; the previous year's comparable quarter had faced quieter periods, making the 2025 lift look sharper, although year-to-date trends confirm a broader upward trajectory.
Those who've charted multi-year data point to a pattern where remote growth consistently outpaces traditional segments, a shift that's been building since post-pandemic accelerations; it's noteworthy that this quarter's numbers fit right into that narrative, with remote GGY comprising a larger slice of the £4.3 billion pie.
- Remote casinos: Key driver with surging plays.
- Lotteries: Strong ticket sales amid draws.
- Land-based slots: £680 million, stable output.
- Overall adult participation: Locked at 48%.
This list captures the essentials, but the interconnections matter too, as crossovers between remote and land-based keep the ecosystem humming.
Implications for Operators and Regulators
Operators poring over these stats in April 2026 have adjusted playbooks accordingly, ramping up remote investments while bolstering land-based perks to retain locals; the steady participation rate, drawn from the Gambling Survey for Great Britain, reassures that the audience base remains solid, allowing focus on yield-per-player metrics.
Regulators, for their part, use such quarterly drops to fine-tune oversight, ensuring growth doesn't outpace harm prevention measures; data from Wave 3 underscores how participation stability aids in targeted interventions, where resources go to at-risk segments rather than broad sweeps.
There's this case from prior quarters where similar upticks prompted enhanced affordability checks, and experts expect echoes here, given the remote surge; it's not rocket science, but aligning compliance with expansion keeps the sector on even keel.
Yet, as the financial year progresses toward March 2026, all eyes stay on Q3 data to see if this momentum holds; summer sports and holiday lotteries could amplify things, while economic headwinds might temper spending, though current figures suggest resilience.
Broader Context and Steady Patterns
Zooming out, the £4.3 billion mark slots into a series of quarterly gains, with researchers noting how GGY has compounded over recent years; land-based stability at £680 million for slots exemplifies a segment that's adapted through tech upgrades like cashless systems, drawing repeat visits without chasing explosive growth.
People who've studied participation trends appreciate the 48% plateau, as it contrasts with yield jumps and highlights operator savvy in monetizing loyalty; online lotteries, for one, have seen app-based sales boom, making draws accessible anytime, which data confirms boosts overall engagement.
And so, while remote casinos steal headlines with their climbs, the full report from the UK Gambling Commission weaves a tale of balanced progress; that's the reality as of April 2026, with stakeholders dissecting every angle for the path forward.
Conclusion
The UK Gambling Commission's Q2 2025-26 stats, released amid April 2026 discussions, confirm a thriving industry at £4.3 billion GGY, propelled by remote casinos and lotteries yet anchored by stable land-based slots and unwavering 48% adult participation; data like this not only tracks financial health but guides the nuanced dance between innovation and responsibility, setting the stage for whatever Q3 brings next.
Turns out, in a market this mature, steady growth with consistent player numbers spells long-term viability; observers await the next quarterly pulse to gauge if the dice keep rolling hot.