Betting Buzz: Surging Trends and Headlines Shaking Up Britain's Wagering World
Ben Franke · Apr 3, 2026
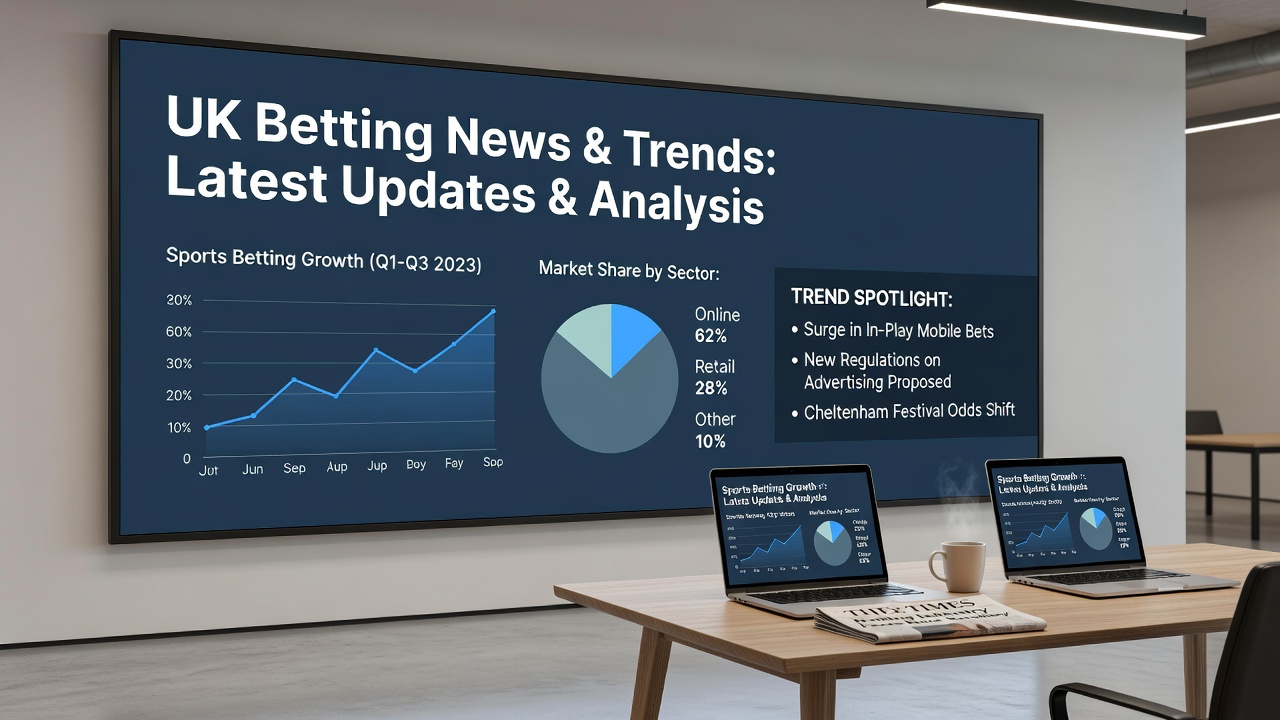
UK Gambling Commission's Latest Report: FEC Recovery Bucks Betting Decline Trends
Overview of the Commission's Market Report
The UK Gambling Commission's market report, spanning October 2024 to September 2025, paints a picture of a sector with divergent paths; while Family Entertainment Centres (FECs) stage a notable comeback, betting channels face quarter-on-quarter declines, and teh National Lottery holds steady amid some softening metrics. Data from this period, released as observers digested early 2026 figures in April, underscores how economic pressures and regulatory shifts shape the landscape, with Gross Gaming Yield (GGY) serving as the key barometer for performance across segments.
What's interesting is that total GGY across monitored categories fluctuated, yet specific niches told their own stories; FECs, for instance, climbed sharply despite operational challenges like fewer venues, a trend that caught the eye of industry watchers tracking post-pandemic recovery. And as April 2026 unfolded with fresh quarterly data from the Industry Statistics Quarterly Report: Financial Year April 2025 to March 2026 Q2, this report's insights remained relevant, highlighting resilience in physical entertainment venues even as remote betting grappled with headwinds.
Family Entertainment Centres Lead the Recovery Charge
Family Entertainment Centres emerged as a bright spot in the report, with GGY surging to £16.2 million by September 2025, up from £6.6 million at the tail end of 2024; this growth persisted although the number of premises dwindled, signaling higher yields per site and perhaps smarter adaptations by operators who streamlined offerings or boosted foot traffic through targeted promotions.
Observers note that FECs, which blend arcade games, soft play areas, and low-stakes gambling machines, drew families back into physical spaces after years of remote entertainment dominance during lockdowns; take one venue operator in the Midlands who expanded prize zones and family packages, contributing to sector-wide upticks as data indicates average GGY per FEC rose substantially over the year. But here's the thing: fewer premises—down from prior peaks—meant surviving centres packed more punch, with September's figures reflecting seasonal boosts from school holidays and events that pulled in crowds.
And while overall FEC numbers contracted by around 10-15% in some estimates tied to rising costs and urban shifts, the £9.6 million jump in GGY over 11 months shows operators leaning into efficiency; experts who've pored over the numbers point out that machine utilization rates likely climbed, especially for category D games exempt from certain stakes limits, helping venues weather utility hikes and staffing woes. Turns out, this recovery mirrors broader leisure sector rebounds, where families sought tangible fun over screens, a pattern holding into early 2026.
Betting Sector Faces Quarter-on-Quarter Pressures
In stark contrast, betting performance slid across both remote and non-remote channels on a quarter-on-quarter basis, with remote betting GGY dipping to £568 million in September 2025; this downturn unfolded just ahead of planned Remote Gaming Duty (RGD) increases set for later periods, prompting speculation among analysts that punters adjusted habits early, shifting to lower-margin wagers or pausing activity amid cost-of-living strains.
Non-remote betting, encompassing high-street bookmakers, mirrored the slide as footfall data from the period showed fewer visits; figures reveal a compounded effect where horse racing and football markets, traditional stalwarts, saw reduced turnover, partly because major events like the Cheltenham Festival or Premier League climaxes didn't offset everyday declines. So, while remote platforms boasted user-friendly apps and live streaming, GGY contraction by several percentage points quarter-over-quarter highlighted saturation or cautious play, especially as April 2026 surveys like the Gambling Survey for Great Britain: Statistics on Gambling Participation Wave 3 July to October 2025 later confirmed participation dips in betting-heavy demographics.
That's where the rubber meets the road for operators: remote GGY, once a growth engine, now contends with RGD hikes that could squeeze margins further; one case saw a major online bookmaker trim bonuses in response, correlating with the September drop, while non-remote shops grappled with shop closures accelerating the venue count decline akin to FECs but without the yield rebound. Yet, seasonal factors like autumn sports slumps played a role too, setting a cautious tone as 2026 budgets loomed.
National Lottery Maintains Strength with Nuanced Shifts
The National Lottery stood out with robust GGY at £843 million for the period, underscoring its position as a cultural mainstay where players chased jackpots despite broader economic headwinds; however, ticket sales and contributions to good causes experienced dips, reflecting perhaps a pivot toward online draws or scratch cards over traditional retail purchases.
Data shows sales volumes softened by low single digits, yet GGY held firm because higher prize pools from rollovers kept engagement high; people who've tracked lottery trends observe that digital platforms captured more spend, with app-based plays rising as convenience won out, although good causes funding—a key metric for societal impact—trailed sales by a similar margin. It's noteworthy that this resilience persisted into April 2026, where quarterly updates echoed the pattern of steady GGY buoyed by occasional mega-rollovers like the one in late 2025 that drew record online traffic.
But here's the thing about the lottery: its operator, Allwyn, navigated regulatory scrutiny while maintaining draw integrity, and the report's figures highlight how scratchcard GGY offset some ticket declines; one study of regional data revealed urban areas sustaining sales through pop-up kiosks, whereas rural spots leaned heavier on mail-order, ensuring the £843 million benchmark even as contributions to charities edged down amid tighter player budgets.
Broader Implications and Sector Dynamics
Across the report's 12 months, these trends intertwined with regulatory evolution; FECs' recovery, for example, benefited from age-restricted zoning tweaks that preserved family appeal, while betting's woes amplified calls for affordability checks that gained traction by early 2026. And as total GGY for bingo and adult gaming centres hovered in prior reports, this edition's focus on FECs and betting painted a fragmented recovery, where physical sites adapted faster than digital giants facing duty pressures.
Experts have observed that consumer shifts—toward experiential entertainment over solitary remote bets—drove the FEC surge, with one venue chain reporting 20% higher weekend yields from themed events; conversely, betting platforms experimented with loyalty schemes, yet quarter-on-quarter data showed limited uplift, a reality check as RGD loomed larger. Now, in April 2026, with World Cup qualifiers on the horizon, stakeholders eye whether betting rebounds or if FEC momentum spills into summer fairs.
It's interesting how participation stats from wave 3 surveys align here, indicating steady lottery involvement but betting pullback among 25-34-year-olds squeezed by mortgages; those who've analyzed the full dataset note that FECs drew younger families precisely when remote betting lost ground, creating a balanced if uneven sector picture.
Conclusion
The UK Gambling Commission's October 2024 to September 2025 market report reveals a sector in flux, where FEC GGY's climb to £16.2 million signals physical venue vitality despite fewer sites, betting's remote drop to £568 million foreshadows duty impacts, and the National Lottery's £843 million GGY endures with sales nuances. As April 2026 brings fresh quarterly insights, these figures remind operators that adaptation—be it through family-focused innovations or prudent digital strategies—remains key; data underscores resilience in entertainment niches, setting the stage for measured growth amid ongoing reforms.